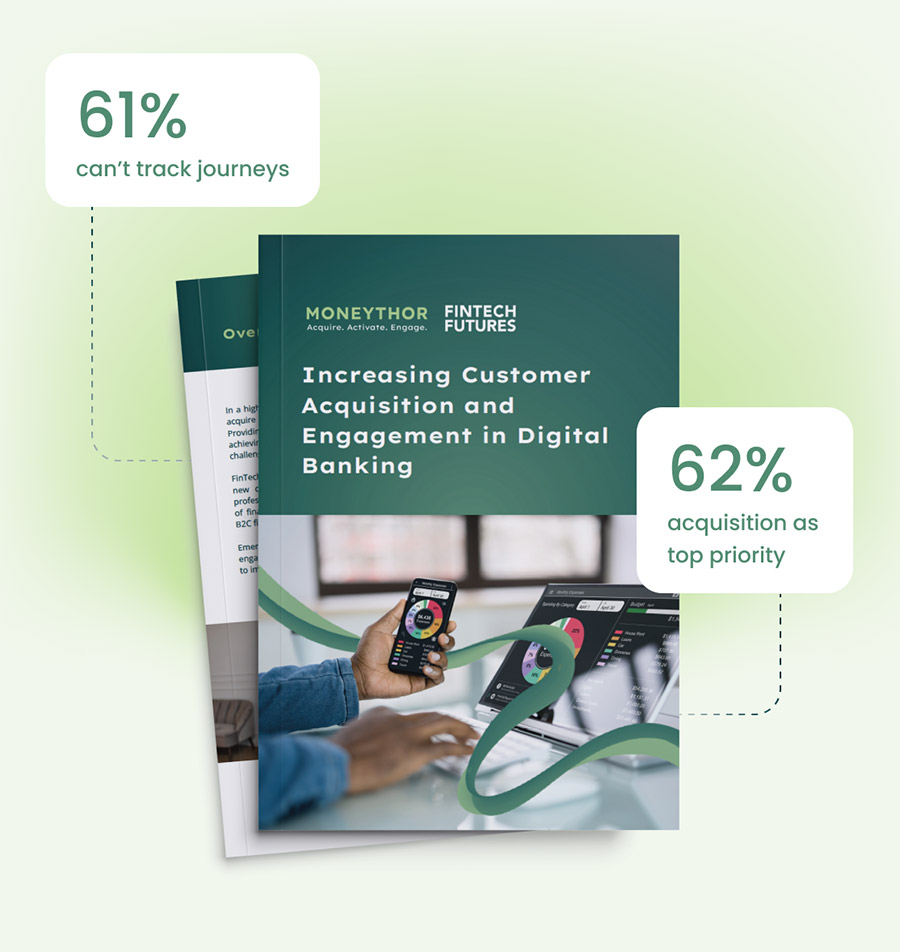
New research from Fintech Futures and Moneythor on why banks struggle with customer acquisition and engagement, and how leading institutions use data and AI to improve activation, retention, and profitability.
What You’ll Learn About the Industry’s Biggest Digital Banking Challenges
This report explores the biggest challenges in digital banking customer acquisition, onboarding, and engagement, and what top-performing banks do differently.

62% of financial institutions say acquiring new customers is their top priority for the next 12 months, yet 74% rate their own acquisition efforts as only moderately successful. The report unpacks the gap between ambition and outcome.

Why customers drop off in the first 90 days after onboarding, and why it takes a mean of 12 months before a new customer becomes profitable. Understanding this window is where most banks are leaving money on the table.

Why organic and referral-based customer acquisition outperforms paid digital channels in banking, and why 39% of banks still do not have a structured referral programme in place to capitalise on it.

The technology barriers preventing personalised digital banking experiences at scale, and what an integrated approach to customer activation looks like in practice.
Why Customer Engagement Is the Biggest Challenge in Digital Banking
Despite heavy investment in digital banking platforms, many banks still struggle with customer engagement, onboarding, and personalisation at scale.
Most banks are good at acquiring customers. Far fewer are good at keeping them.
Acquisition is only half the equation. According to the survey, 61% of banking professionals struggle to track the customer journey effectively, 55% cannot deliver personalised banking experiences at scale, and 49% fail to sustain engagement beyond onboarding. These are not isolated technology gaps. They are the predictable result of digital banking platforms built to process transactions, not build relationships.
The commercial consequence is clear. New customers take up to 12 months to become profitable, and 15% drop off within the first three months. Every gap in the activation journey is acquisition spend that never converts.
The banks closing this gap are not spending more, they are using transaction data, AI, and real-time personalisation to drive customer activation and long-term engagement.