Booster, a NZ $9B investment manager and non-bank challenger, launched Booster Savvy using Moneythor’s personalisation engine to transform saving behaviours from an occasional activity into a daily financial habit. Through personalised insights, automated savings journeys, and behavioural nudges, Booster has achieved stronger customer engagement, deposit growth, and primary-account behaviour amongst its customers.
Case Study
How Booster Used Personalisation to Drive Savings Growth and Customer Engagement
The Challenge
Competing for Financial Relationships and Deposit Growth
Booster is one of New Zealand’s largest investment managers and, in recent years, has been challenging the traditional banking model. As competition for customer attention, share of wallet, and deposits intensifies across banking, fintech, and wealth management, Booster recognised that simply offering another savings product would not be enough.
Customers often spread their financial lives across multiple providers, making it difficult to build engagement, grow balances, and establish a primary financial relationship. Booster wanted to create an experience that encouraged customers to spend, save, and invest through a single platform, while helping them build stronger financial habits along the way.
To achieve this, they needed a way to deliver personalised experiences that remained relevant long after onboarding and gave customers a reason to return, engage, and save more consistently.
The Solution
Personalisation as the Engagement Engine
Booster partnered with Moneythor to build a personalised savings experience designed to drive long-term engagement, reinforce positive financial behaviours, and help customers grow balances and save more consistently.
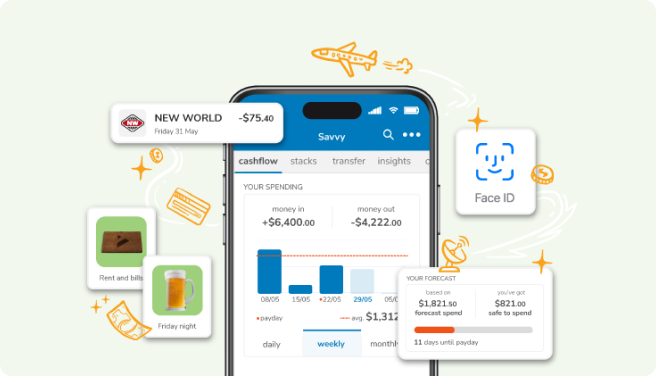
Rather than relying on broadcast campaigns or generic push notifications, Moneythor powers a real-time engagement layer that turns each customer’s transaction data into personalised insights, recommendations, and actions.
Key capabilities:
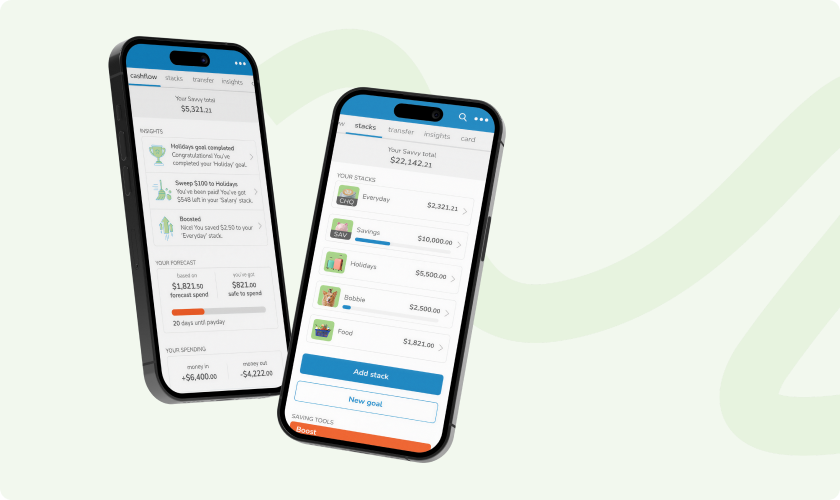
- Turn saving into a habit – By analysing customer spending behaviour, income patterns, and transaction activity in real time, Moneythor delivers contextual nudges and personalised prompts that encourage customers to act at the moments that matter most.
- Automate positive financial behaviours – Savvy customers can choose from multiple automated saving mechanisms, including Boost roundups, Sweep transfers, salary-triggered savings contributions, and cashflow-based automation. These experiences reduce friction and make saving a natural part of everyday banking.
- Deliver personalised financial guidance – Transaction-aware insights help customers make more informed financial decisions while creating ongoing reasons to engage with the platform.
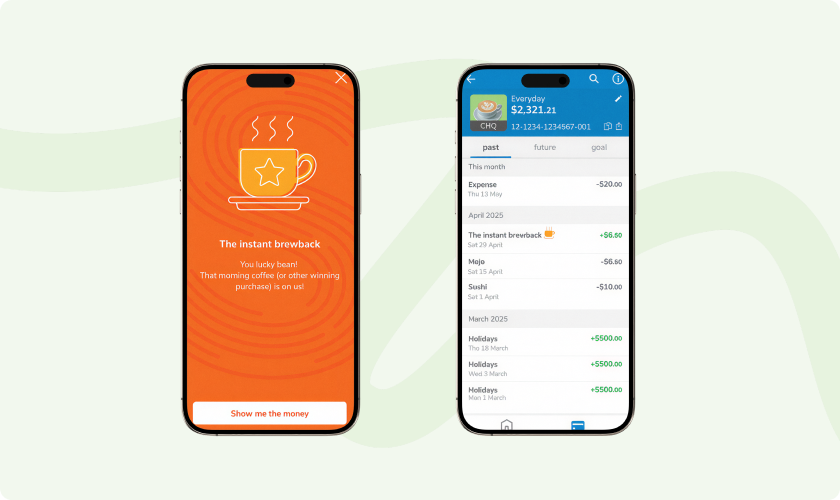
- Increase primary-account engagement – Gamification, progress visualisation, personalised challenges, and behavioural nudges encourage customers to use Savvy as an everyday spending and saving account rather than a secondary financial product.
- Launch quickly on production-ready infrastructure – Moneythor’s API-first architecture enabled Booster to deploy personalisation capabilities quickly without rebuilding core systems.
The Results
Engagement That Compounds
By embedding personalisation, automation, and behavioural design directly into the customer experience, Booster has turned saving from a passive activity into an ongoing habit, encouraging customers to engage more frequently, save more effortlessly, and build deeper relationships with the platform over time.

active Savvy customers

moved into savings through automation

customer returns

1 in 5 Savvy customers have automated their savings with Boosts

Customers average more than 3 stacks (savings goals)

Save an extra ~$200 per pay cycle with Sweep
About Booster
Booster is a New Zealand-owned investment manager founded in Wellington in 1998, managing approximately $9B on behalf of New Zealanders. Booster has a track record of category innovation, including the Booster Innovation Fund (early-stage retail investment) and Booster Savvy (investment account with linked debit card). Booster is not a registered bank; Savvy is not a bank account.
Latest case studies
Discover how Moneythor helps banks acquire, activate, and engage customers through personalised digital banking experiences.